This article is a general overview, not insurance or legal advice. Coverage needs vary, so work with a licensed insurance agent who writes commercial auto transport policies.
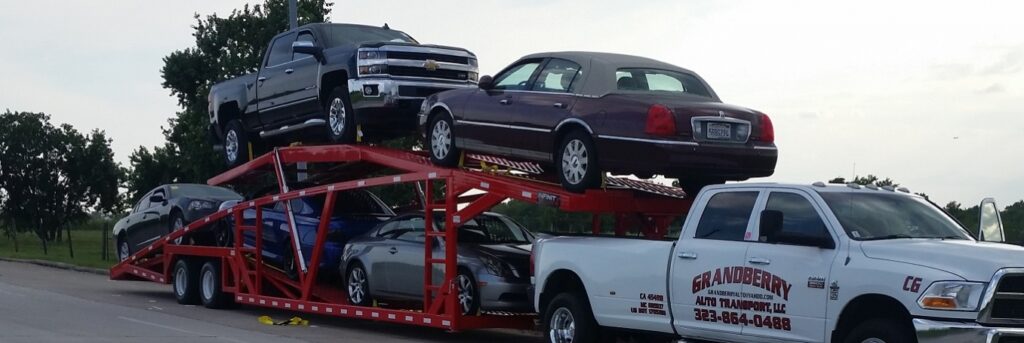
Insurance is one of the biggest monthly costs of running a car hauler, and one of the most confusing. New owner-operators often aren’t sure what’s legally required, what customers will ask for, and why quotes for the same truck and trailer can be so far apart. This guide covers the coverage types car haulers usually carry, the federal and Texas minimums, what affects your premium, and how to shop smart before you buy your 4, 5 or 6 car hauler.
What’s legally required
Interstate (federal)
For-hire carriers of general property in vehicles of 10,001 lb or more must carry at least $750,000 in public liability insurance for interstate work. Your insurance company files proof with FMCSA on Form BMC-91 or BMC-91X, and your operating authority won’t go active until that filing is in place. A car hauler pulling a loaded multi car trailer is well over the 10,001 lb line.
Texas intrastate
If you haul only inside Texas and your truck and trailer combination is rated over 26,000 lb, you’ll need a TxDMV number and proof of at least $500,000 in liability insurance on file with the Texas Department of Motor Vehicles. Our car hauler authority checklist covers both sets of registrations.
What about cargo insurance?
Here’s what surprises many people: federal rules don’t require cargo insurance for ordinary for-hire property carriers. FMCSA dropped that requirement in 2011 and kept it only for household goods movers. In practice, though, almost every dealer, auction and broker will require cargo coverage before they hand you a car. For a car hauler, cargo insurance is a must, even though the law doesn’t list it.
Coverage types car haulers usually carry
| Coverage | What it covers | Who requires it |
|---|---|---|
| Auto liability | Injuries and damage you cause to others on the road | Federal law (interstate), TxDMV (Texas intrastate) |
| Motor truck cargo | Damage to or loss of the vehicles you’re hauling | Customers: dealers, auctions and brokers |
| Physical damage | Damage to your own truck and car hauler trailer | Usually your lender if you finance |
| General liability | Claims from your business that aren’t on the road, such as at a customer’s lot | Some customers and facilities |
| Occupational accident or workers’ comp | Injuries to you or your drivers on the job | Depends on your setup and state rules |
Why car hauler insurance costs more
Insurers price auto transport differently from general freight for a few reasons:
- High-value cargo. A full load can be worth more than the truck and trailer combined, and every vehicle is individually identifiable. A small scratch can become a claim.
- Multiple vehicles at once. One incident can involve several cars.
- Loading and unloading. Ramps, decks and tight dealer lots add chances for damage that a sealed van doesn’t have.
- New authorities. Underwriters have no history to go on for a new company, so first-year pricing is usually the highest.
What affects your premium
- Driving record and experience, especially time in commercial vehicles.
- Years in business and your claims history.
- Cargo limits you choose and the deductible.
- Where you operate and where the truck is parked.
- How far you run, local and regional versus long-haul.
- The value of your truck and trailer for physical damage coverage.
- Your safety practices, such as documented inspections, securement and condition reports.
How to shop for car hauler insurance
- Start early. Get quotes before you buy equipment, so insurance is part of your budget, not a surprise.
- Ask your customers first. Find out what liability and cargo limits your dealers, auctions and brokers require, and quote to those numbers.
- Use an agent who knows auto transport. Car hauler cargo is a specialty, and an agent who writes it regularly will know which companies to approach.
- Compare more than price. Read the cargo exclusions and conditions carefully, such as requirements around securement, unattended trailers, theft and the value per vehicle.
- Make sure the cargo limit covers a full load, not just one car, especially on a 5 or 6 car hauler.
- Re-shop at renewal. As your record and time in business build, your options usually improve.
Habits that help keep claims (and premiums) down
- Do a walk-around and take time-stamped photos of every vehicle at pickup and delivery, and have both sides sign the condition report.
- Strap every vehicle properly. See our guide to car hauler securement rules.
- Keep up with daily inspections and annual inspections on the truck and trailer. Our DOT inspections guide explains what to keep on file.
- Only take loads from brokers and shippers you’ve verified. Our article on double brokering and fraud shows how.
Frequently asked questions
How much insurance do I need to haul cars?
For interstate for-hire work, the federal minimum is $750,000 in liability. For Texas-only work over 26,000 lb, TxDMV requires at least $500,000. Customers will usually also require cargo coverage, so ask them what limits they need.
Is cargo insurance required by law?
Not federally, for car haulers. FMCSA only requires cargo insurance for household goods movers. Most customers require it anyway, so plan on carrying it.
Why are my quotes so different?
Insurers weigh experience, records, cargo limits, deductibles and operating area differently, and not every company wants auto transport business. That’s why working with an agent who knows the car hauler market matters.
Plan your full startup budget
Insurance is one line in the full picture. See our breakdown of what it costs to start a car hauling business, compare our 4 car, 5 car and 6 car hauler trailers for sale in Texas, or contact Infinity Trailers in Haslet.
Last reviewed November 18, 2026.
Sources: